The CREATE MORE Act (Republic Act 12066) lets enterprises, including foreign-owned ones, that register an approved project in the Philippines pay no income tax for 4 to 7 years, then 5% of gross income or a 20% rate on taxable income after enhanced deductions for 10 or 20 more years. This guide summarizes the rules as of 20 Oct 2026, marks which figures are verified and which are not, and links to a free calculator.
Independent guide, not advice. Independent summary, not legal or tax advice. Built from statute text and published commentary; items marked Unverified or Per seminar deck have not been confirmed against primary sources. Manila Open House Homes is not a law or tax firm and is not affiliated with PEZA, BOI, FIRB or any government agency. Confirm eligibility and rates with your investment promotion agency and a Philippine tax adviser before relying on any figure.
How to read the labels: Verified Per seminar deck Unverified Our analysis Approximate
Up to 27 yrsMaximum incentive period. FIRB bracket: 7 ITH + 20 post-ITH; bonus years can add more.Verified[1]
What the law does
RA 12066 amends Title XIII of the National Internal Revenue Code (the CREATE Act, RA 11534). It sets income tax holidays, a 5% special corporate income tax or enhanced deductions, VAT and duty relief for registered business enterprises whose activity is listed in the Strategic Investment Priority Plan. Verified[1]
Only a registered business enterprise qualifies, and its activity must be listed in the Strategic Investment Priority Plan (SIPP). An investment promotion agency (IPA) such as PEZA or BOI approves projects with capital of PHP 15 billion or less, with a decision due within 20 working days and one extension of up to 20 more. The Fiscal Incentives Review Board (FIRB) approves projects above PHP 15 billion. Verified[1]
RA 12066 amends the CREATE Act (RA 11534), enacted in March 2021; that date is taken from the seminar deck and not re-sourced here. Per seminar deck Two thresholds recur below: an export enterprise exports at least 70% of annual output, and a high-value domestic market enterprise (DME) has capital above PHP 15 billion or export sales of at least US$100 million in the prior year. Verified[1]
How long the incentives last
The income tax holiday (ITH) depends on the SIPP tier of the activity and on where the project is located. The darker the cell, the longer the holiday. Verified[1, 5]
| SIPP tier | NCR | Metro or contiguous areas | All other areas | Total with 10 post-ITH years |
|---|---|---|---|---|
| Tier I | 4 yrs | 5 yrs | 6 yrs | 14 to 16 yrs |
| Tier II | 5 yrs | 6 yrs | 7 yrs | 15 to 17 yrs |
| Tier III | 6 yrs | 7 yrs | 7 yrs | 16 to 17 yrs |
Approval brackets
| Approver | Capital | ITH | After the ITH | Status |
|---|---|---|---|---|
| Investment promotion agency (PEZA, BOI, etc.) | Up to and including PHP 15 billion | 4-7 | 10 years SCIT or EDR (export) / 10 years EDR (domestic) | Verified[1, 2] |
| Fiscal Incentives Review Board (FIRB) | Above PHP 15 billion | 4-7 | 20 years SCIT/EDR (export) / 20 years EDR (domestic and high-value DME) | Verified[1] |
| President (Sec. 301) | At least PHP 50 billion or at least 10,000 direct local jobs within 3 years | Negotiated | Extensions only for projects with at least 10,000 direct local employees, capped at 5 years (Sec. 296) or 10 years (Sec. 296-A) | Verified[1] |
| High-value domestic market enterprise (DME) | Capital above PHP 15 billion, or export sales of at least US$100 million in the prior year | 4-7 | EDR only; 0% VAT on local purchases and import exemption | Verified[1, 2] |
Bonus years exist: relocating fully out of NCR adds 3 years and conflict or disaster areas add 2 (Sec. 296) Verified[1]. The reported 8-year cap on the ITH and the 40-year overall cap come from a single secondary source and were not found in the statute extraction. Unverified[5]
5% special rate or enhanced deductions
After the holiday, an export enterprise chooses between the Special Corporate Income Tax (SCIT) and the Enhanced Deductions Regime (EDR); a domestic market enterprise can use the EDR only. The choice is irrevocable, and the two cannot be combined. Verified[1, 2] The regular corporate income tax rate is 25%, the EDR rate is 20% and the SCIT rate is 5% of gross income. Verified[1, 6]
| Feature | SCIT | EDR | Status |
|---|---|---|---|
| Who can use it | Export enterprises only (at least 70% of annual output exported) | Export enterprises and domestic market enterprises | Verified[1, 2] |
| Tax basis | 5% of gross income earned | 20% of taxable income after enhanced deductions | Verified[1, 7] |
| Replaces | All national and local taxes | Regular 25% CIT only; a local tax of up to 2% of gross income (RBELT) can still apply | Verified[1] |
| Switching | Choice is irrevocable; cannot be combined with EDR | Cannot be granted at the same time as SCIT. A domestic market enterprise may elect EDR from the start of commercial operations | Verified[2] |
Worked example: exporter in a non-metro location
Take a Tier I export enterprise outside NCR and metro areas, with PHP 5 billion of capital, PHP 300M gross income and PHP 150M net income a year, over a 16-year horizon. It gets 6 ITH years and then 10 SCIT years. Our analysis
| Period | Regular 25% tax | With CREATE MORE |
|---|---|---|
| Years 1 to 6 (ITH) | PHP 225M | PHP 0 |
| Years 7 to 16 (SCIT) | PHP 375M | PHP 150M |
| Total over 16 years | PHP 600M | PHP 150M |
| Saving | PHP 450M (75%) | |
The EDR works differently. With PHP 150M of net income and PHP 100M of enhanced deductions, the tax is 20% of PHP 50M, or PHP 10M a year, against PHP 37.5M at the 25% regular rate. With PHP 100M of enhanced deductions, EDR tax is 20% x (150M - 100M) = PHP 10M a year versus PHP 37.5M at the 25% regular rate. The seminar deck's PHP 30M baseline used 20%, which is the EDR rate, not the regular rate. Our analysis
The enhanced deductions
| Deduction | Additional | Status |
|---|---|---|
| Additional depreciation: buildings | 10% | Unverified[8, 9] |
| Additional depreciation: machinery and equipment | 20% | Unverified[8, 9] |
| Research and development (local spend, approved proposal) | 100% | Unverified[8, 9] |
| Training (IPA-approved, direct Filipino employees) | 100% | Unverified[8, 9] |
| Power expense (actual electricity cost, registered operations) | 100% | Verified[1, 8] |
| Labor expense (direct local employees in registered activity) | 50% | Unverified[8, 9] |
| Domestic input expense (needs at least 50% value-addition) | 50% | Unverified[8, 9] |
| Reinvestment allowance (manufacturing, tourism) | up to 50% | Verified[1, 8] |
| Trade fairs and missions (IPA-approved export promotion) | 50% | Verified[1, 8] |
| Enhanced NOLCO | — | Verified[1, 8] |
Power at 100% additional means 200% in total, raised from 50% under CREATE. The reinvestment allowance ends for availments after 31 December 2034. Trade fairs and enhanced NOLCO are not modelled in the calculator. Rows marked unverified rest on secondary sources only; check Sec. 294(C).
Compliance tightens in 2026. For taxable years ending 31 December 2026 onward, EDR enterprises must substantiate their deductions and file a Notarized Comprehensive Summary Report with the IPA, and related-party deductions are disallowed unless at arm's length. Verified[8, 10]
Try your own numbers.
The free calculator and dashboard models these rules with your inputs and shows the same status labels.
Open the interactive calculator & dashboard
The free calculator and dashboard models these rules with your inputs and shows the same status labels.
Open the interactive calculator & dashboard
VAT, duties and local taxes
Beyond income tax, registration changes how value-added tax, import duties and local taxes apply.
- Imports directly attributable to the registered project. Import VAT and duty exemption (Sec. 294(D)-(E)); PEZA MC 2025-052 lists goods deemed directly attributable. Verified[1, 11]
- Local purchases by registered export enterprises. 0% VAT regardless of location. Verified[1, 2]
- Sales to ordinary DMEs. 12% VAT unless otherwise exempt. Verified[1]
- Registered Business Enterprise Local Tax (RBELT). Not more than 2% of gross income for RBEs in ITH or EDR; not imposed under SCIT (Sec. 294(F)). Verified[1]
- Dividends and branch profits. Sources conflict: 25% final on dividends to non-resident foreign corporations, reducible to 15% under tax-sparing or treaty; 15% branch profit remittance tax with possible exemption for registered activities. Not resolved. Unverified[12]
Which activities qualify
An activity must be listed in the SIPP or the application is automatically disapproved (Sec. 300). The SIPP is valid for 3 years subject to review. Verified[1] The 2026 plan is DTI/BOI Memorandum Order No. 47, signed 21 May 2026 and released 2 June 2026, but we read only two published summaries of it, and they differ. Unverified[13, 14]
| Tier | Summary A (Philstar) | Summary B (Ocampo & Suralvo) |
|---|---|---|
| Tier 1 | Agriculture, fishery and forestry; manufacturing; halal, kosher and organic activities; services; health care and disaster risk reduction; infrastructure, logistics and energy; waste, water and climate projects. | Agriculture, value-adding manufacturing, healthcare, IT-BPM, aircraft MRO, environmental infrastructure. |
| Tier 2 | Defense-related services, industrial value chain gaps, food security. | IC design, oil refining, critical minerals processing, EV components and infrastructure, renewable energy, energy-efficient vessels and aircraft, defense services. |
| Tier 3 | Science, technology and innovation. | R&D, patent commercialization, AI and data science, quantum, aerospace, cybersecurity, biotech, startup ecosystems. |
Also covered: export activities, special-law activities, area-specific priorities. Tourism is registered through TIEZA (34 projects worth PHP 14.5B registered under CREATE and CREATE MORE since 2021).
Sector examples from the seminar deck Per seminar deck are semiconductors and electronics, pharmaceuticals and processed food in Tier I; desalination and sustainable aviation in Tier II; and highly technical advanced manufacturing in Tier III. These may reflect the 2022 SIPP (MO 61) or the 2024 amendment rather than MO 47. Check the activity code in the current SIPP before relying on a tier.

Announced demand shows where activity is heading: Philippine AI+ Infrastructure Masterplan 2026-2033: US$34.4B needed, about 1.5 GW of data-center capacity targeted by 2033 Verified[15]; BOI approvals 2025: energy PHP 970.09B, mass housing PHP 241.65B, transport and storage PHP 230.06B Verified[16].
Investment data behind the pitch
Net FDI inflows were US$8.925 billion in 2023, US$9.398 billion in 2024 and US$7.791 billion in 2025, which is a five-year low yet above the BSP's US$7 billion projection. Verified[17, 3]
Approval figures tell a different story. PEZA approved PHP 175.709 billion in 2023 and PHP 260.89 billion in 2025 (314 projects, 78,741 jobs) Verified[18, 4], and PHP 140.69 billion in the first half of 2026 against a PHP 300 billion target Verified[19]. The 2024 PEZA figure of about PHP 214 billion is Unverified and left out of any chart. BOI approvals were PHP 1.62 trillion in 2024 and PHP 1.56 trillion in 2025 (322 projects, 40,175 jobs; foreign portion PHP 149.45 billion) Verified[16]; the 2023 BOI figure of about PHP 1.26 trillion is Unverified. PSA counts PHP 546.19 billion of foreign approvals across all agencies in 2024 and PHP 272.38 billion in 2025. Verified[20]
Source: Grant Thornton ASEAN Tax Guide 2026, with Trading Economics (Singapore) and TaxAtlas (Vietnam). Verified[21, 22, 23, 6]
On headline rates the Philippines is the highest of the six at 25%, and the regional comparison rests on a single source. Vietnam's 20% is topped up to a 15% minimum for large multinationals, and Indonesia's figure is also single-source. Registration is what changes the comparison: an export enterprise on SCIT pays 5% of gross income, but that is a tax on revenue and is not comparable with a headline rate on profit. Verified[21, 1]
Who is investing? The BSP lists Japan, the United States, Singapore and South Korea as the main sources of 2025 equity placements Verified[3]. PSA's fourth-quarter 2025 approvals were led by the Netherlands (PHP 33.05 billion), Japan (PHP 17.88 billion) and Singapore (PHP 17.66 billion) Verified[24], and PEZA's first-half 2026 top sources were the Netherlands, South Korea, Singapore, Indonesia, Germany and Japan Verified[19]. A full-year 2025 country ranking is not available. Unverified
Where location changes the answer
Because the holiday is shortest in NCR and longest elsewhere, location matters as much as the sector. The table lists hotspots that have a sourced fact, with the bracket we assign. Approximate
| Hotspot | Bracket | Sourced fact |
|---|---|---|
| Metro Manila / NCR | NCR Verified | Subway partial operations are reported for 2027, 2028 or 2032 depending on the source (unverified). NSCR Valenzuela-Malolos phase targeted for late 2027 and the Clark extension for 2H 2028. Unverified[25] |
| Calamba / Santa Rosa / Biñan / Cabuyao, Laguna | Metro or contiguous Unverified | The LGUs are named in the TIEZA list. PLDT's 11th data center, a PHP 5B build, is in Laguna. Verified[26] |
| Dasmariñas / Imus / Bacoor, Cavite | Metro or contiguous Unverified | Average Cavite lot prices reached about PHP 20,000/sqm (sale) at end-2025. CALAx status not found. Unverified[27] |
| Cainta / Antipolo / Taytay, Rizal | Metro or contiguous Unverified | BOI is assisting Singapore's SpaceDC on a US$700M data center in Cainta (Sept 2025). Verified[28] |
| Meycauayan / San Jose del Monte, Bulacan | Metro or contiguous Unverified | Named in the TIEZA list. NSCR phase 1 ends at Malolos, Bulacan. Verified[25] |
| Batangas (port, LIMA, Lipa) | All other areas Our analysis | A Batangas ecozone development was among two new ecozone projects worth PHP 5.9B combined in H1 2026. LIMA specifics not found in this research. Verified[29] |
| Clark Freeport / New Clark City, Pampanga-Tarlac | All other areas Our analysis | BCDA reported PHP 49.96B in approved investments in H1 2026; investors named include Lufthansa Technik Philippines, FedEx and UPS, with an AI hub planned. A US$2.7B hyperscale campus is cited for New Clark City. Verified[30] |
| Subic Bay Freeport, Zambales | All other areas Our analysis | The Luzon Economic Corridor links Subic, Clark, Manila and Batangas. No Subic-specific figure found. Verified[29] |
| Metro Cebu: Cebu IT Park, Mactan (Lapu-Lapu) | Metro or contiguous Unverified | A US$200M nitrile glove project (South Luzon and Cebu, 2,000 jobs) and a Cebu export manufacturing venture are in PEZA's 2026 pipeline. Whether Mactan counts as metro is unclear. Verified[29] |
| Metro Davao | Metro or contiguous Unverified | Named in the TIEZA list. No sourced investment facts found. Unverified[26] |
| Cagayan de Oro / Misamis (PHIVIDEC) | All other areas Our analysis | A Misamis Occidental ecozone was among the two new ecozones worth PHP 5.9B in H1 2026. PHIVIDEC specifics not found. Verified[29] |

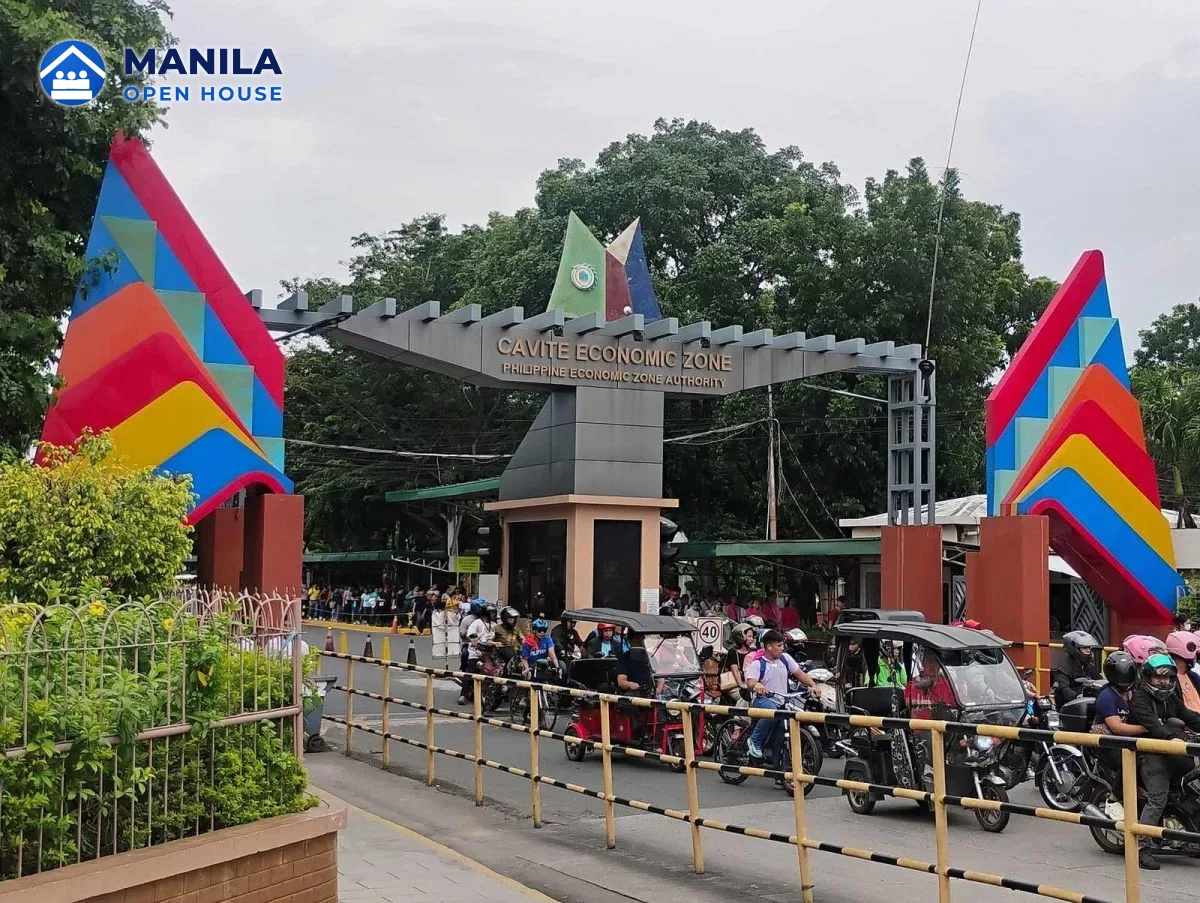

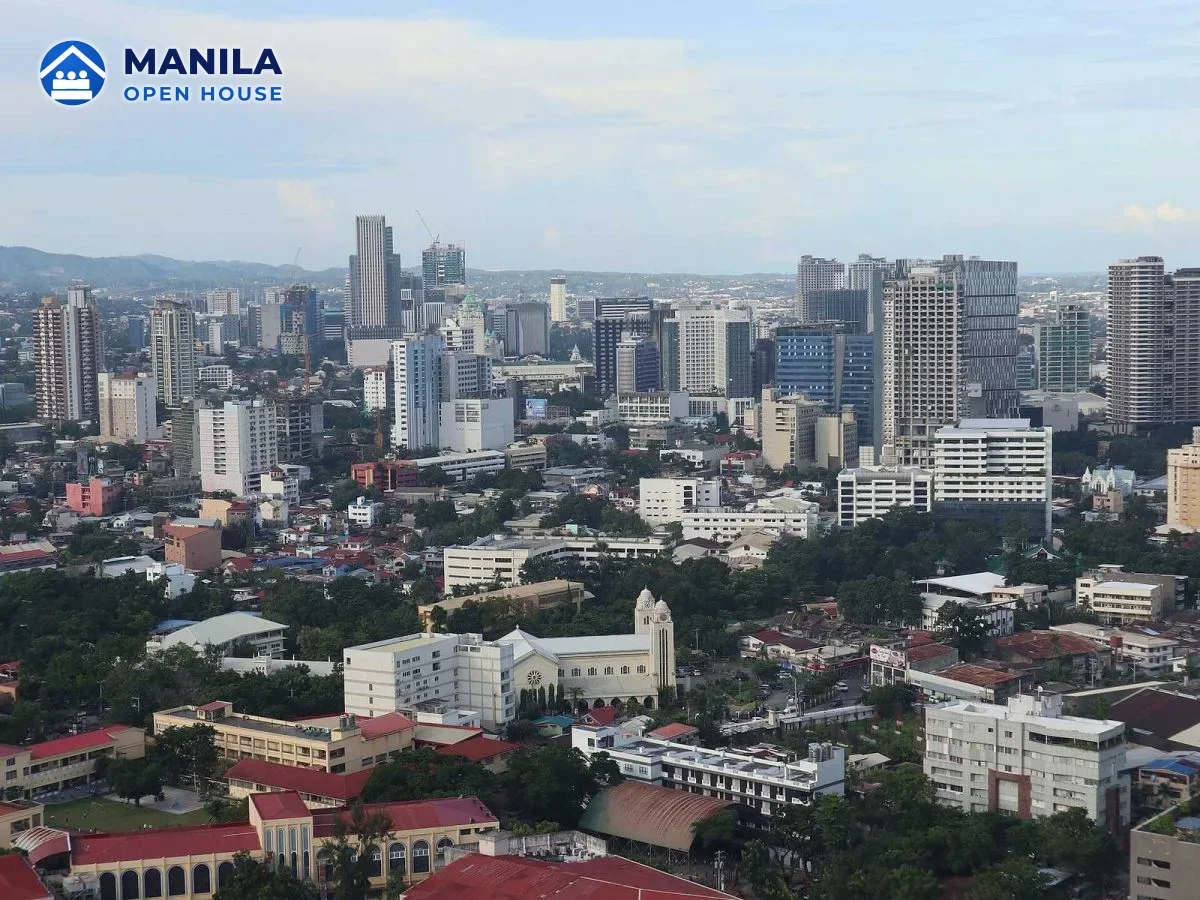

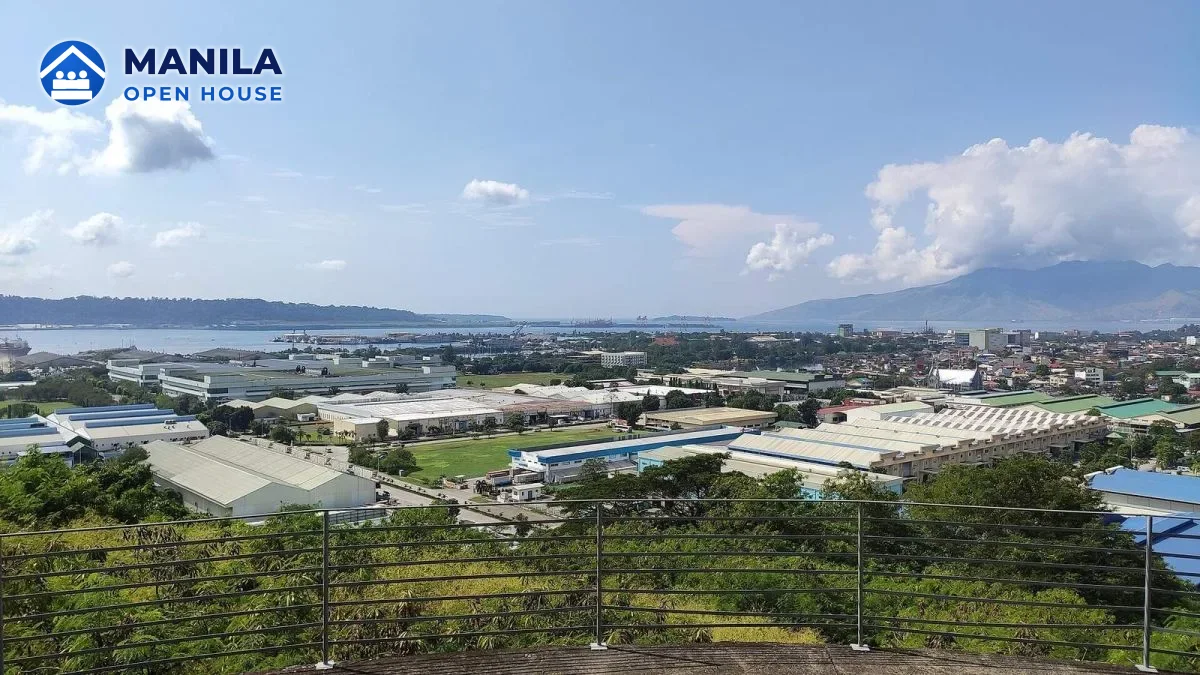

Hotspot rows for Silang and Tagaytay, Bataan and Iloilo carry no sourced facts, and Davao is on the TIEZA list with no investment facts found. Whether a project is NCR, metro or other is settled at registration, not by a map. For one industrial example outside the metro bracket, see our independent guide to Aboitiz Economic Estates industrial lots, which applies this table to four estates.
Timeline
| Date | Event | Status |
|---|---|---|
| Mar 2021 | CREATE Act (RA 11534) enacted | Per seminar deck |
| 8 or 11 Nov 2024 | RA 12066 (CREATE MORE) signed | Unverified[31, 32, 1] |
| 27 Nov 2024 | Law takes effect | Verified[33] |
| 17 Dec 2024 | FIRB interim IRR (Advisory 007-2024) | Verified[34] |
| 17 Feb 2025 | Final IRR signed (effective 20 Feb 2025 on publication); FIRB Advisory 001-2025 | Verified[35, 36] |
| 25 Feb 2025 | BIR RR 10-2025 on VAT (numbering conflicts across sources) | Unverified[37] |
| 25 Apr 2025 | BIR RMC 42-2025 circularizes the IRR | Verified[36] |
| 21 May / 2 Jun 2026 | 2026 SIPP (MO 47) signed / released | Verified[13] |
| 22 Jul 2026 | FIRB Advisory 010-2026 circularizes DOF Order 026-2026 (EDR terms) | Verified[8] |
| 29 Sep 2026 | BIR RMC 105-2026 posted; notarized summary report mandatory for taxable years ending 31 Dec 2026 onward | Verified[8, 10] |
| 31 Dec 2034 | Reinvestment allowance availment ends; pre-CREATE 5% GIT holders may keep it until this date | Verified[1, 8] |
Where sources disagree
Four of the open conflicts in our research are listed here.
- 20% versus 25% corporate income tax. The deck's EDR example used 20%. Verified[1, 6]
- Metro and contiguous area list. The list comes from the TIEZA FAQ and secondary sources, not the IRR text. Unverified[26]
- Domestic market enterprise post-ITH period: 10 years or 5. The statute text and Forvis Mazars say 10 years of EDR after the ITH. Unverified[1, 2, 5, 38]
- ITH cap of 8 years and 40-year total. One secondary source states them; we did not find them in the statute extraction. Unverified[5]
What this means for you
- Start with the activity code in the current SIPP, not the seminar deck's examples. The tier decides the holiday length.
- Treat the location bracket as provisional until your IPA confirms it. A move from NCR to an area outside metro can add up to two ITH years in the table above.
- Decide early whether you are an export enterprise. SCIT is only for exporters, and the choice between SCIT and EDR is irrevocable.
- Budget for the 2026 compliance burden if you take the EDR: substantiation, a notarized summary report, and arm's-length related-party deductions.
- Do not rely on anything marked unverified above. Dividend withholding, the ITH cap, several deduction percentages and the metro list all need professional confirmation.
Next steps. Model your own case in the interactive CREATE MORE calculator & dashboard. Looking at land inside an ecozone? Read our buyer's guide to Aboitiz Economic Estates (an independent guide, not an advertisement) or browse the Manila Open House Premium pages.
Frequently asked questions
How long can incentives last?
Up to 14 to 17 years for projects up to PHP 15 billion approved by an investment promotion agency (4 to 7 years of income tax holiday plus 10 years), and 24 to 27 years for projects above PHP 15 billion approved by the FIRB. Relocating fully out of NCR adds 3 years and conflict or disaster areas add 2, subject to the cap. Verified[1]
Is the 5% SCIT available to domestic-market companies?
No. SCIT is for export enterprises, meaning at least 70% of annual output is exported. Domestic market enterprises receive the income tax holiday and then the enhanced deduction regime (20% on taxable income after enhanced deductions). Verified[1, 2]
Does location change the incentive?
Yes. The income tax holiday is shorter in NCR (4 to 6 years) than in metro or contiguous areas (5 to 7) or other areas (6 to 7). The list of metro and contiguous LGUs used here comes from the TIEZA FAQ and has not been checked against the IRR. Unverified[1, 26]
Photo credits
- Makati / Bonifacio Global City skyline — Lawrence Ruiz, CC BY-SA 4.0, via Wikimedia Commons
- Laguna Technopark / CALAX — LMP 2001, CC BY-SA 4.0, via Wikimedia Commons
- Cavite Economic Zone, Rosario — Ralff Nestor Nacor, CC BY-SA 4.0, via Wikimedia Commons
- Cebu IT Park / Cebu City skyline — Patrickroque01, CC BY-SA 4.0, via Wikimedia Commons
- Subic Bay Freeport Zone — Alankang, CC BY-SA 4.0, via Wikimedia Commons
- Semiconductor / clean-room manufacturing (non-Philippine) — Aileen Devlin/Jefferson Lab from Newport News, USA, Public domain, via Wikimedia Commons

All photos are illustrative and show places or industries named in the article; none is a property for sale. Photos licensed CC BY-SA 4.0 are shared under that licence; two are public domain as marked.
Sources
- RA 12066 statute text (Lawphil) — lawphil.net/statutes/repacts/ra2024/ra_12066_2024.html (accessed 20 Oct 2026)
- Forvis Mazars Philippines: CREATE MORE Act tax alert — forvismazars.com/ph/en/insights/tax-alerts/create-more-act (accessed 20 Oct 2026)
- Philstar: FDI inflows fall to five-year low (12 Mar 2026) — philstar.com/business/2026/03/12/2513605/fdi-inflows-fall-five-year-low (accessed 20 Oct 2026)
- Philstar: PEZA investment approvals hit P261 billion (25 Dec 2025) — philstar.com/business/2025/12/25/2496593/peza-investment-approvals-hit-p261-billion (accessed 20 Oct 2026)
- ASEAN Briefing: How location affects tax incentives in the Philippines (19 Aug 2026) — aseanbriefing.com/news/how-location-affects-tax-incentives-for-investments-in-the-philippines/ (accessed 20 Oct 2026)
- Batas Natin: resident foreign corporation tax, Sec. 28(A) under CREATE — batasnatin.com/doctrine/tax-resident-foreign-corp-Sec-28-A-25-CREATE (accessed 20 Oct 2026)
- Grant Thornton Philippines: The CREATE MORE Act (RA 12066) — grantthornton.com.ph/insights/articles-and-updates1/lets-talk-tax/the-create-more-act-ra-12066-a-new-chapter-for-tax-incentives-and-economic-development-in-the-philippines/ (accessed 20 Oct 2026)
- Grant Thornton: DOF Department Order 026-2026 (Enhanced Deduction Regime) — grantthornton.com.ph/technical-alerts/tax-alert/2026/circularizing-department-of-finance-dof-order-no-026-2026-on-the-terms-and-conditions-on-the-grant-of-the-enhanced-deduction-regime/ (accessed 20 Oct 2026)
- NDV Law: enhanced deductions regime — ndvlaw.com/how-to-lower-your-corporate-tax-to-20-with-the-create-more-enhanced-deductions-regime/ (accessed 20 Oct 2026)
- KPMG Philippines: Special InTax, August 2026 — kpmg.com/ph/en/insights/2026/08/special-intax-august-2026-issue-1-volume-1.html (accessed 20 Oct 2026)
- PwC Philippines: But wait, there is more for exporters under CREATE MORE — pwc.com/ph/en/tax/tax-publications/taxwise-or-otherwise/2025/but-wait-theres-more-for-exporters-under-create-more.html (accessed 20 Oct 2026)
- PwC Tax Summaries: Philippines withholding taxes — taxsummaries.pwc.com/Philippines/Corporate/Withholding-taxes (accessed 20 Oct 2026)
- Philstar: Marcos OKs 2026 investment promotion blueprint (3 Jun 2026) — philstar.com/funfare/2026/06/03/2532436/marcos-oks-2026-investment-promotion-blueprint (accessed 20 Oct 2026)
- Ocampo & Suralvo: BOI approves the 2026 SIPP (30 Jul 2026) — ocamposuralvo.com/2026/07/30/boi-approves-the-2026-strategic-investment-priority-plan/ (accessed 20 Oct 2026)
- TechRepublic: Philippines AI infrastructure timeline and data centers — techrepublic.com/article/news-apac-philippines-ai-infrastructure-timeline-data-centers/ (accessed 20 Oct 2026)
- PortCalls: BOI-approved investments in 2025 reach P1.56T — portcalls.com/boi-approved-investments-in-2025-reach-p1-56t/ (accessed 20 Oct 2026)
- PIDS: FDI net inflows inch up 0.1% in 2024 — pids.gov.ph/details/news/in-the-news/fdi-net-inflows-inch-up-0-1-in-2024 (accessed 20 Oct 2026)
- Tribune: PEZA secures P19.5B approved investments (14 Dec 2023) — tribune.net.ph/2023/12/14/peza-secures-p19-5-b-approved-investments (accessed 20 Oct 2026)
- PortCalls: PEZA approved investments almost double to P140B in H1 2026 — portcalls.com/peza-approved-investments-almost-double-to-p140b-in-h1/ (accessed 20 Oct 2026)
- Philippine Statistics Authority (via PortCalls): PSA approved foreign investments 2025 — portcalls.com/ph-approved-investments-down-2-in-2025-foreign-ventures-fall-50 (accessed 20 Oct 2026)
- Grant Thornton Vietnam: ASEAN Tax Guide 2026 (PDF) — grantthornton.com.vn/globalassets/__shared__/0618-asean-tax-guide-2026.pdf (accessed 20 Oct 2026)
- Trading Economics: Singapore corporate tax rate — tradingeconomics.com/singapore/corporate-tax-rate (accessed 20 Oct 2026)
- TaxAtlas: Vietnam corporate tax — taxatlas.io/country/vietnam/corporate-tax (accessed 20 Oct 2026)
- Tribune: Approved foreign investments hit P10.3B in Q4 2025 — tribune.net.ph/2026/02/12/approved-foreign-investments-hit-p103-billion-in-q4-2025 (accessed 20 Oct 2026)
- Context.ph: NSCR timeline — context.ph/?p=76793 (accessed 20 Oct 2026)
- TIEZA FAQ: fiscal incentives for TIEZA-registered enterprises (metro/contiguous LGU list) — tieza.gov.ph/what-are-the-fiscal-incentives-available-to-tieza-registered-business-enterprises/ (accessed 20 Oct 2026)
- Inquirer Plus: Cavite lot prices — plus.inquirer.net/?p=387675 (accessed 20 Oct 2026)
- Malaya: BOI sees multi-billion peso data center investments — malaya.com.ph/business-news/boi-sees-multi-billion-peso-data-center-investments (accessed 20 Oct 2026)
- Philstar: Ecozone investments nearly double in H1 2026 (30 Jun 2026) — philstar.com/cebu-news/2026/06/30/2538658/ecozone-investments-nearly-double-h1 (accessed 20 Oct 2026)
- Context.ph: BCDA sees P100B investment surge in 2026 — context.ph/2026/09/22/bcda-sees-p100b-investment-surge-in-2026/ (accessed 20 Oct 2026)
- Conventus Law: RA 12066 signed 11 Nov 2024 — conventuslaw.com/?p=123159 (accessed 20 Oct 2026)
- PortCalls: CREATE MORE IRR signed (cites 8 Nov 2024 signing) — portcalls.com/create-more-act-irr-signed/ (accessed 20 Oct 2026)
- Grant Thornton: BIR suspends audits from 16 Dec 2024 (cites 27 Nov 2024 effectivity) — grantthornton.com.ph/insights/articles-and-updates1/tax-notes/bir-suspends-audits-and-field-operations-from-december-16-2024-to-january-12-2025 (accessed 20 Oct 2026)
- SunStar: Interim IRR on availment of incentives — sunstar.com.ph/cebu/tax-notes-interim-irr-on-the-availment-of-incentives-and-transfer-of-registration-under-create-more (accessed 20 Oct 2026)
- Baker McKenzie: DOF and DTI jointly issue the CREATE MORE IRR — insightplus.bakermckenzie.com/bm/tax/philipines-the-department-of-finance-and-the-department-of-trade-and-industry-jointly-issue-the-implementing-rules-and-regulations-of-the-corporate-recovery-and-tax-incentives-for-enterprises-to-maximize-opportunities-for-reinvigorating-the-economy-create-more-act (accessed 20 Oct 2026)
- KPMG Philippines: Special InTax, March 2025 — kpmg.com/ph/en/insights/2025/03/special-intax-march-2025-issue-1-volume-1.html (accessed 20 Oct 2026)
- Philstar: Simplifying VAT refunds under CREATE MORE (6 May 2025) — philstar.com/business/2025/05/06/2440807/simplifying-vat-refunds-and-expanding-incentives-create-more/amp/ (accessed 20 Oct 2026)
- BDB Law: CREATE MORE summary (PDF) — bdblaw.com.ph/images/publications/120424_CREATE_MORE.pdf (accessed 20 Oct 2026)
- DOE slide deck: Registration Procedure under the CREATE Law — doe.gov.ph/sites/default/files/pdf/e_ipo/03%20Registration%20Procedure%20under%20the%20CREATE%20Law.pdf (accessed 20 Oct 2026)
- Context.ph: TIEZA sees tourism investment surge in Q4 — context.ph/2026/09/17/tieza-sees-tourism-investment-surge-in-q4/ (accessed 20 Oct 2026)
- Philstar: US firms exploring IT, logistics investments in ecozones — philstar.com/entertainment/2026/07/18/2542815/us-firms-exploring-it-logistics-investments-ecozones (accessed 20 Oct 2026)
- Supreme Court E-Library: 2022 SIPP (MO 61) — elibrary.judiciary.gov.ph/thebookshelf/showdocs/9/95858 (accessed 20 Oct 2026)
- Context.ph: Skyway-NLEX Connector 2027 — context.ph/2026/03/11/skyway-nlex-connector-seen-to-cut-2-hour-metro-manila-trip-to-30-minutes-by-2027/ (accessed 20 Oct 2026)
Photos
Related articles
CREATE MORE Worked Example: How an Exporter Saves ₱450M in Tax
A registered export manufacturer earning ₱300M gross and ₱150M net a year would pay about ₱600M in income tax over 16 years at the regular 25%. With CREATE…
How Much Real Estate Loan Can You Get? Income, DTI, Down Payment, Banks vs Pag-IBIG vs Business Loans (Philippines 2026)
How big a loan can you really get for a house, a condo or a lot? Lenders do not guess. They look at three numbers: your documented income, how much of it your…
Journal and Ledger: How to Start a Business in the Philippines and Record It the BIR Way (2026)
If you rent out a condo on Airbnb, lease apartments, sell property for a commission, manage other people’s units, or fix and clean them for a living, the BIR…